
Posted On: September 22, 2026 by First Community Bank and Trust in: Community Banking Community Banking Advocacy Community Events Community News General
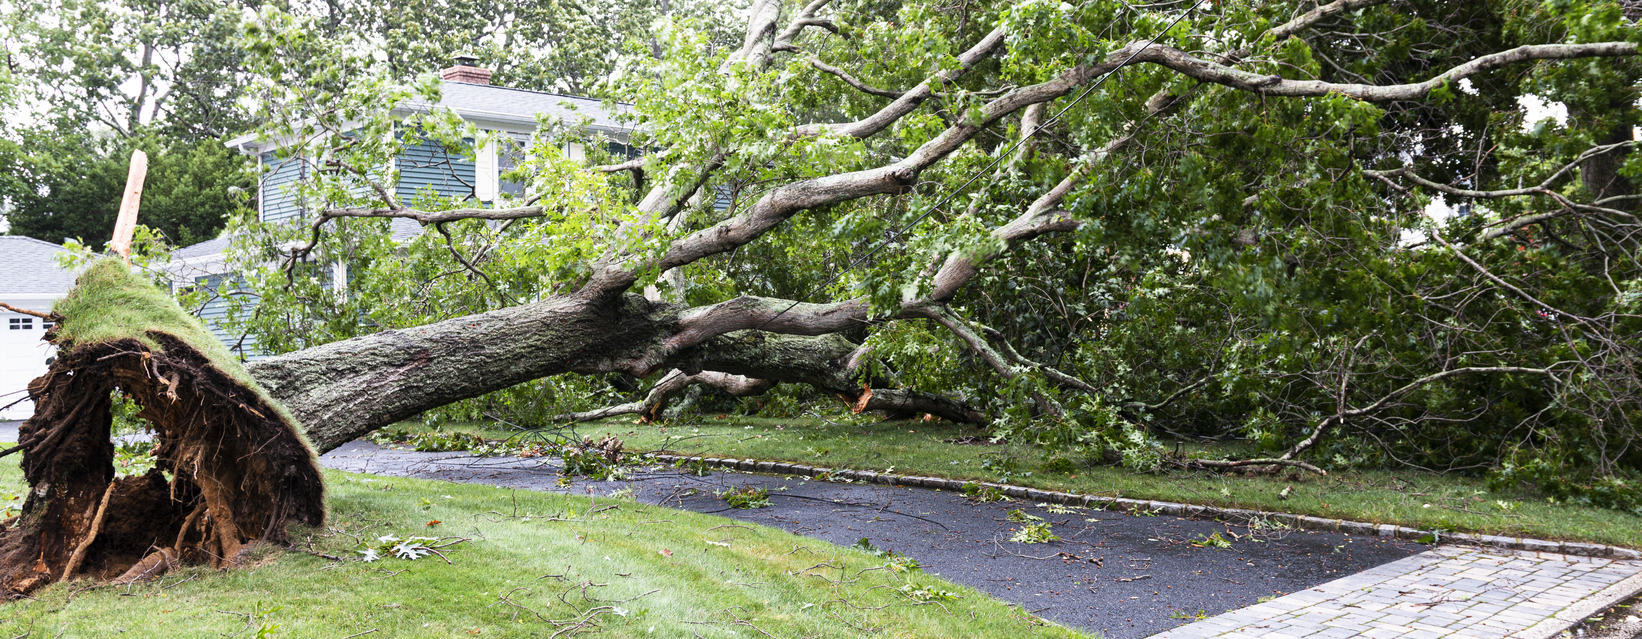
Severe storms can happen with little warning. A damaged roof, fallen tree, broken windows or other unexpected repairs can quickly turn into a significant expense.
When storm damage occurs, your first step should be to document the damage and contact your homeowner’s insurance provider to understand what may be covered.
Review your policy’s coverage limits, deductibles and any exclusions or special deductibles that may apply to storm damage. Keeping photos, receipts and repair estimates can also help you navigate the claims process.
The Consumer Financial Protection Bureau offers helpful guidance for homeowners dealing with the financial impact of a disaster, including steps to take with insurance and other available resources. You can find CFPB’s guidance here: https://www.firstcbt.bank/blog/post/start-recovering-and-rebuilding-your-financial-life
What If Insurance Doesn't Cover Everything?
Even with homeowners insurance, you may have expenses that aren't fully covered. You could be responsible for deductible repairs that fall outside your coverage, costs that exceed policy limits or expenses that arise while waiting for an insurance claim to be resolved.
If you've built equity in your home, a Home Equity Loan or Home Equity Line of Credit (HELOC) from First Community Bank and Trust may be an option to consider.
Already Have a HELOC?
If you already have a Home Equity Line of Credit and have available credit, you may be able to access those funds for eligible expenses without applying for a new loan.
A HELOC provides a revolving source of credit secured by your home. You can borrow what you need when you need it, up to your available credit limit, subject to the terms of your line.
That flexibility can be especially valuable when storm-related expenses are difficult to predict. In addition to addressing unexpected repairs, available HELOC funds may also be used for home improvements or purchases that help prepare your property for future severe weather or power outages, such as a backup generator, battery backup system, roof or window improvements, or other eligible projects.
Don't Have a HELOC? Explore Your Options.
If you don't currently have a home equity line, Wendy Hoekstra, Vice President of Retail Lending can help you determine whether a new HELOC or Home Equity Loan may be right for your situation.
A HELOC provides ongoing access to funds, making it a flexible option when repair costs may change, expenses occur over time or you want access to funds for future projects. Explore CFPB’s What You Should Know About a Home Equity Line of Credit Booklet to learn more.
A Home Equity Loan provides a lump sum, which may be a good fit when you know how much you need and prefer a fixed payment structure.
The option that makes sense for you will depend on factors such as your available home equity, the amount you need, your financial situation and how you prefer to repay the funds.
Turning Your Home's Equity into an Opportunity
A storm can create financial challenges you didn't plan for, but your home's equity may provide a resource to help you respond to unexpected expenses and prepare for what's ahead.
First Community Bank and Trust is your local lender. Whether you already have a home equity line with us or are considering one for the first time, we're here to help you understand your options and find a solution that fits your needs.
Unexpected storm damage or planning ahead for the next one? Let's talk about your options.
Contact Wendy Hoekstra, Vice President of Retail Lending to learn more about our Home Equity Loans and HELOCs, or to discuss how an existing home equity line may be able to help.
Home Equity Loans and HELOCs are subject to credit approval and applicable terms and conditions. Because these products are secured by your home, failure to repay could result in the loss of your home. Please consult your homeowners insurance policy and insurance provider for information regarding coverage for storm-related damage.
About First Community Bank and Trust
First Community Bank and Trust is a privately-owned bank. Established in 1916 First Community Bank and Trust has been serving Beecher, IL, Peotone, IL and the surrounding communities for over 110 years. Our commitment to providing the best banking products and services is matched only by our outstanding customer service. We offer traditional community banking services, including mortgage, consumer, and commercial lending, as well as state of the art electronic banking services.
Press Contact:
Steve Koehn, Senior Vice President
First Community Bank and Trust
(708) 946-2246
###
0 comments